Asking at the right time raised PayPal’s notification opt-in more than 5×
PayPal’s signup asked for everything up front. My team moved the asks to moments that mattered to people, and far more of them said yes.
All screens recreated. The flows, decisions, and results are my team’s.
Asking only in context reaches fewer people. By rough math on PayPal’s public numbers, package tracking still produced about as many opt-ins a day as the signup prompt. The people who said yes there were more likely to stay monthly active, stayed opted in, and went on to use the product. Signup opt-ins often never did.
Signup asked for everything before it gave anything.
Before a new user could do anything useful, PayPal asked for identity, verification, a financial instrument and regulatory sign-offs. The compliance floor was legitimate. Over the years, teams had piled their own asks on top of it to boost their product’s readiness, and no one owned the total the user faced.
Our hypothesis was that a minimal signup would get more people in, faster. Ask only what’s needed to start, and ask for the rest later, when it means something to the person. Users had no reason yet to trust us with an SSN or a bank link, so the maximum signup was asking for the highest-stakes information before we’d earned any of it.
Of the 12 asks that stood before first product use, 2 were needed to start: email and password, and phone verification. The other 10 were better asked later, in context.
People who pushed through learned little about the product. They tapped through confirmations to reach the one task that brought them there, and features plainly on screen didn’t register as available to them.
People knew what PayPal was. They couldn’t tell what it could do for them yet.
Moving to a minimal signup was too big an ask and too big a lift. It was an engineering monolith, with regulatory requirements across hundreds of locales and high engineering risk on any change. Most product teams weren’t willing to risk their product readiness and ability to onboard inline. So we tested smaller ideas downstream, on the surfaces where there was room to move.
Asked cold at signup, few people said yes. Tied to a moment that mattered, far more did.
My onboarding and early-life design team ran the same test on two asks: savings, a product to activate, and push notifications, a permission to opt into. Each time we compared the same ask in two places, cold during signup and at a moment the person already cared about. We A/B tested each ask against the signup version.
Savings
~3% → ~6%
Savings activation
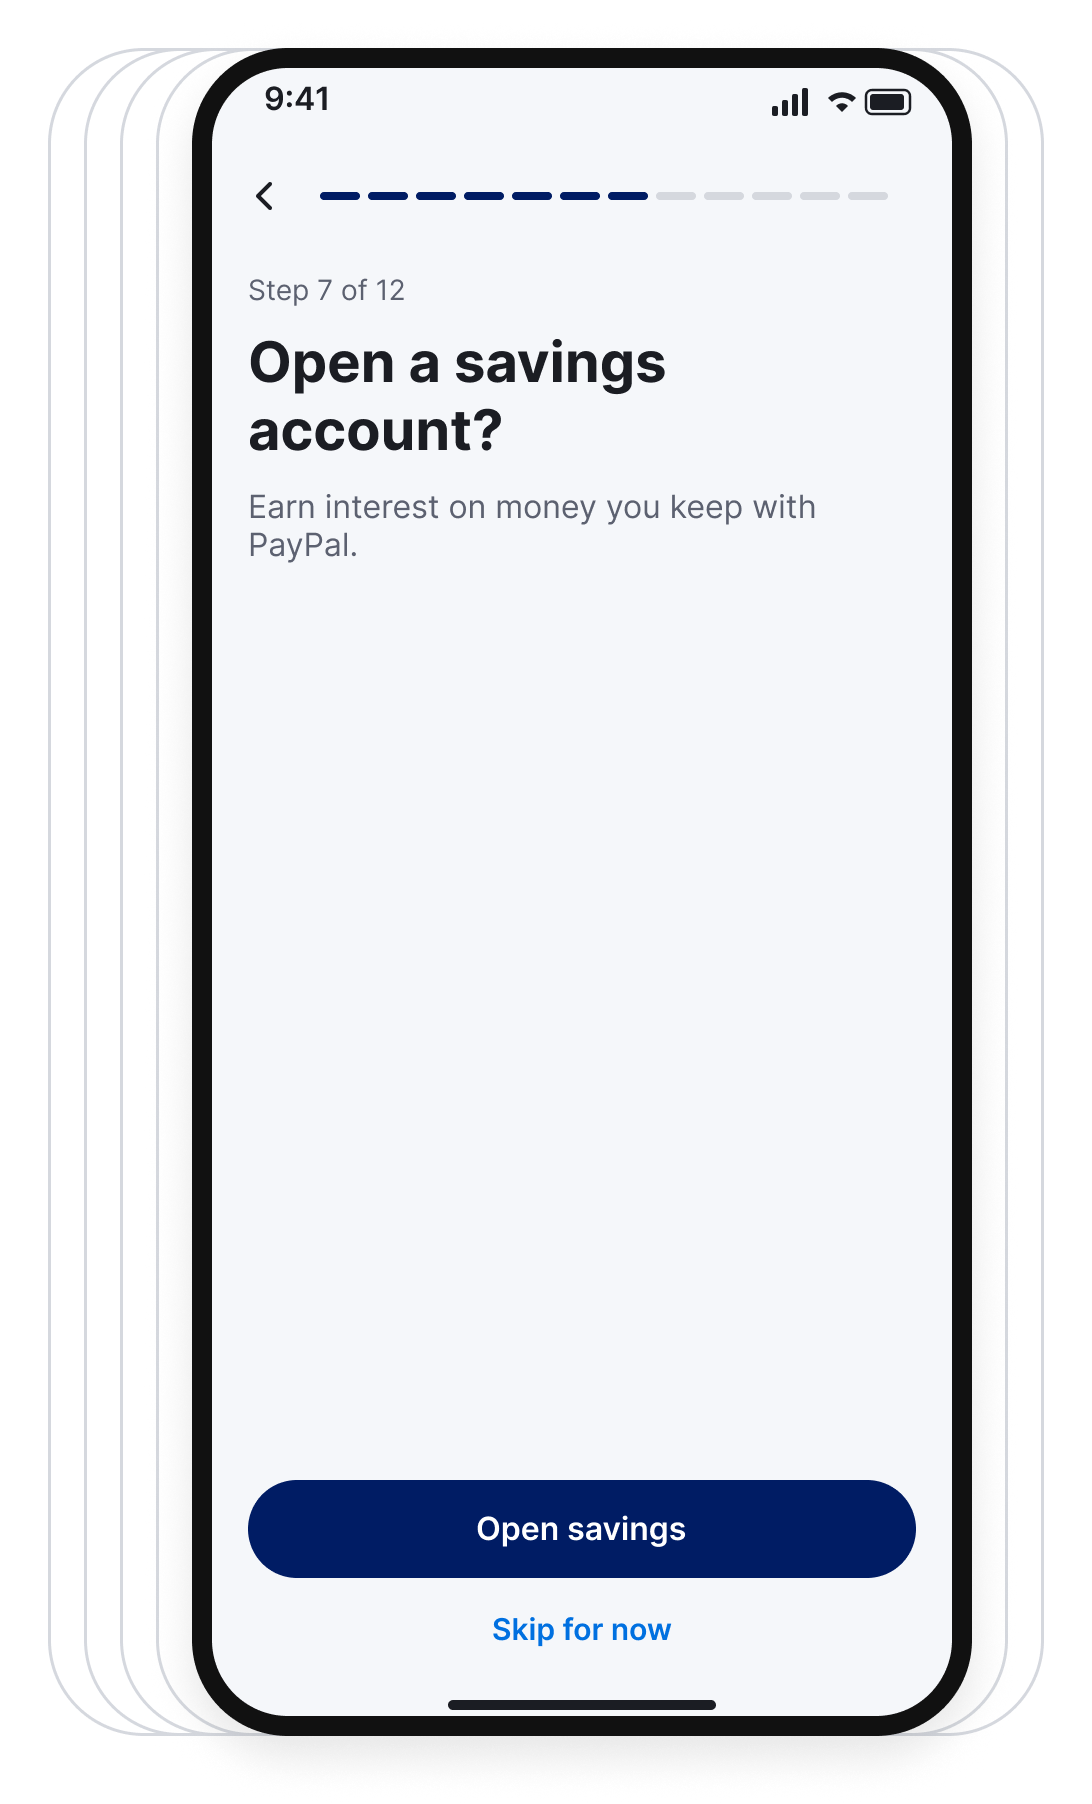
- Cold
- Step 7 of 12 in signup, before the account held any money.
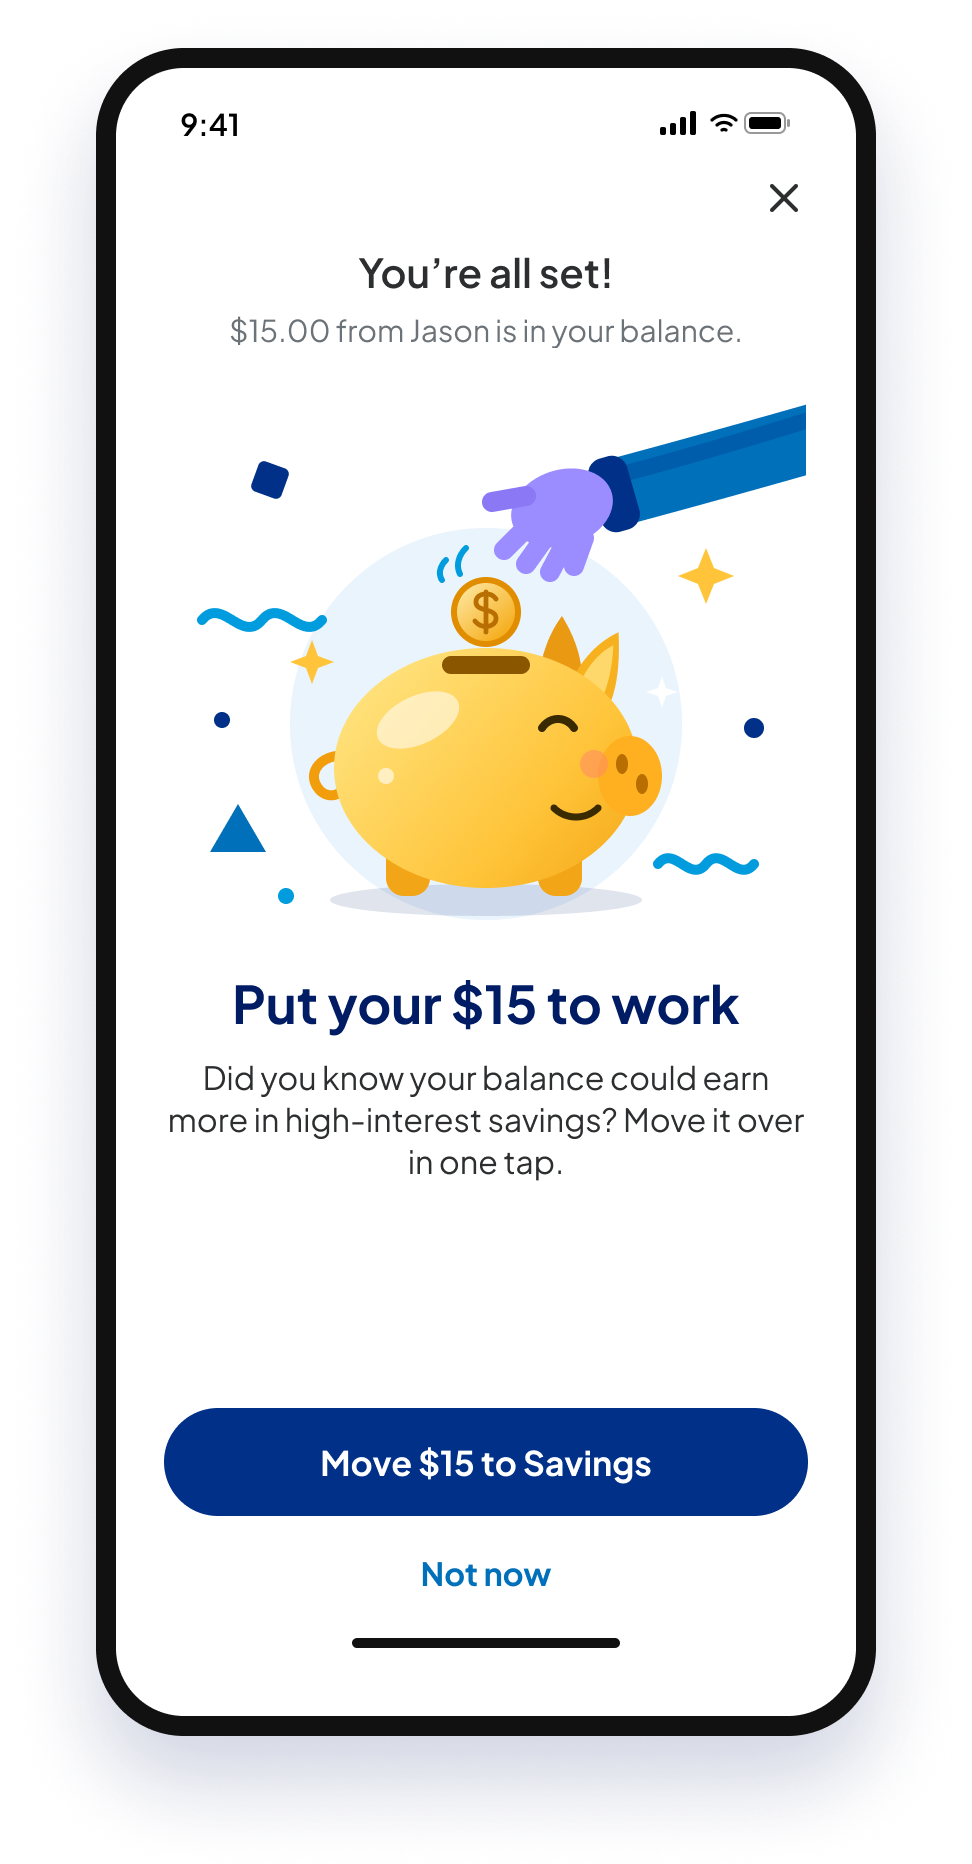
- The moment
- A friend’s $15 lands in the balance.
- Why it worked
- The offer is about money already on screen, so it needs very little explaining. The in-moment group had money in the balance which was the point (it also means the groups differ).
Push notifications
~10% → ~70%
Said yes to the ask
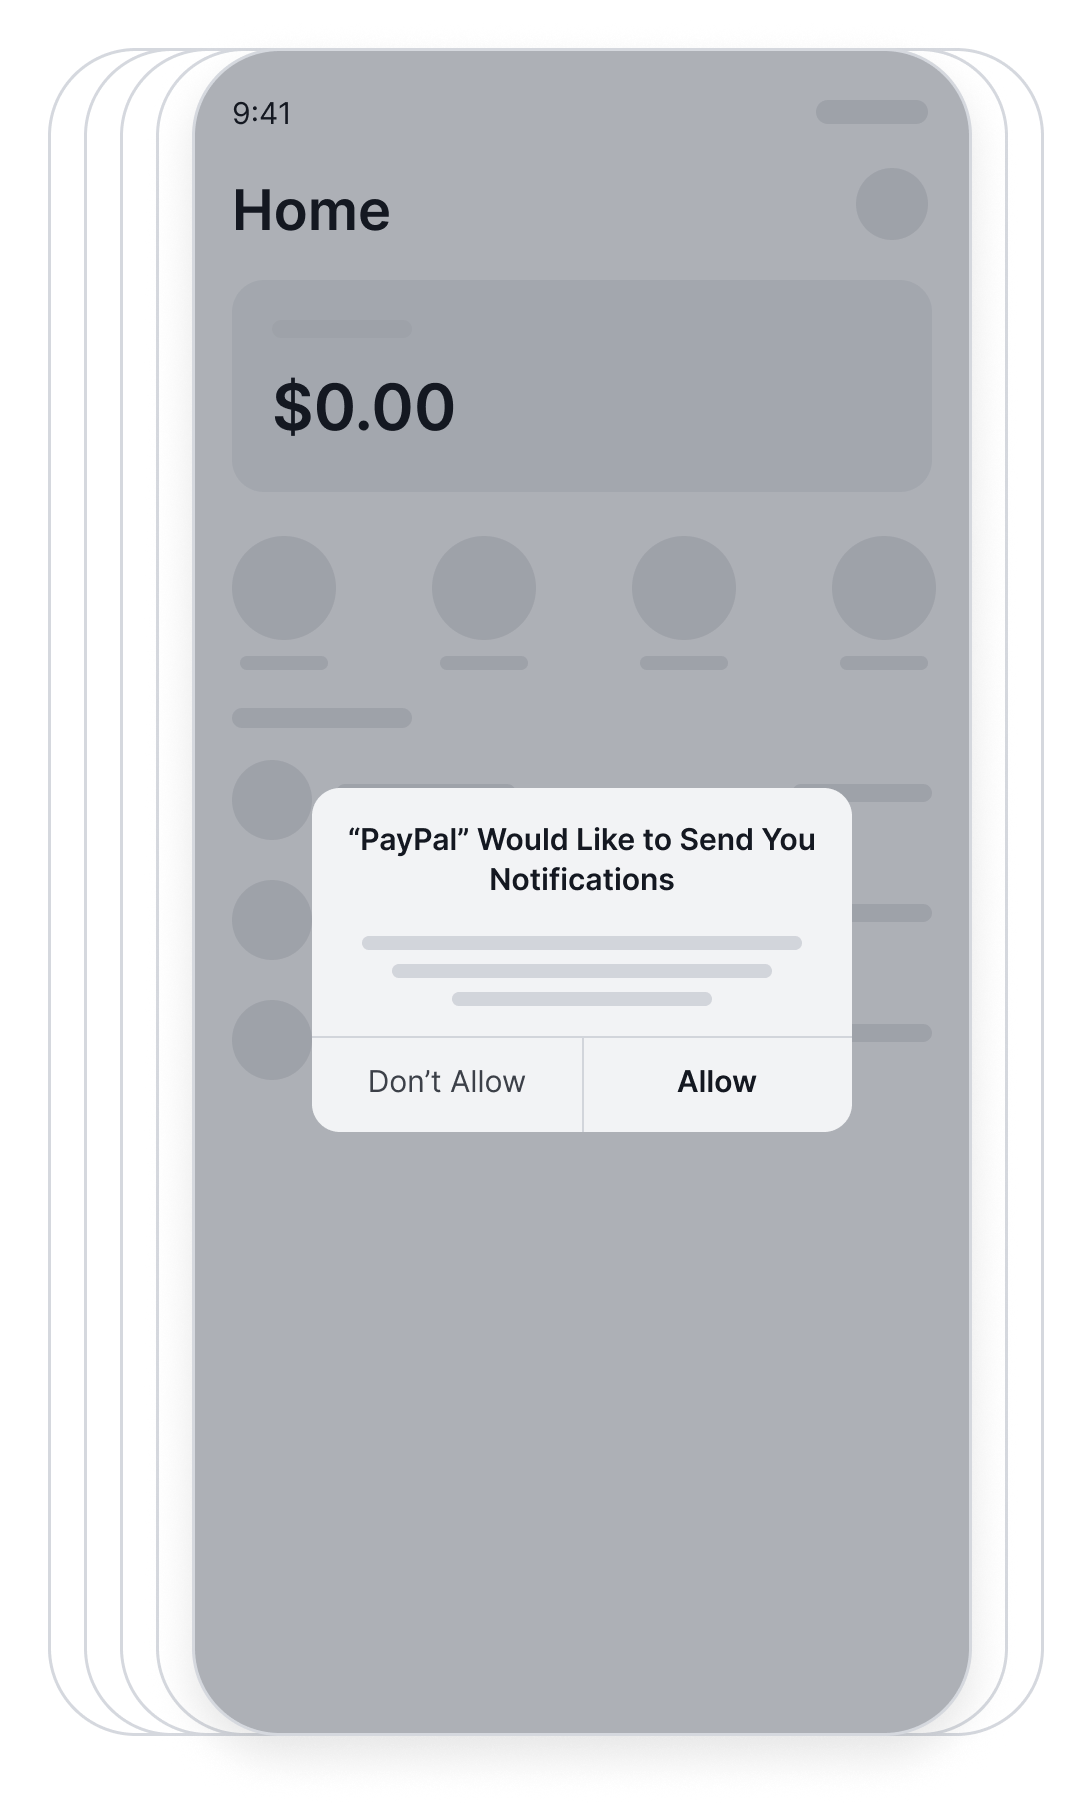
- Cold
- The iOS permission dialog right after account creation, with nothing yet to be notified about.
- The moment
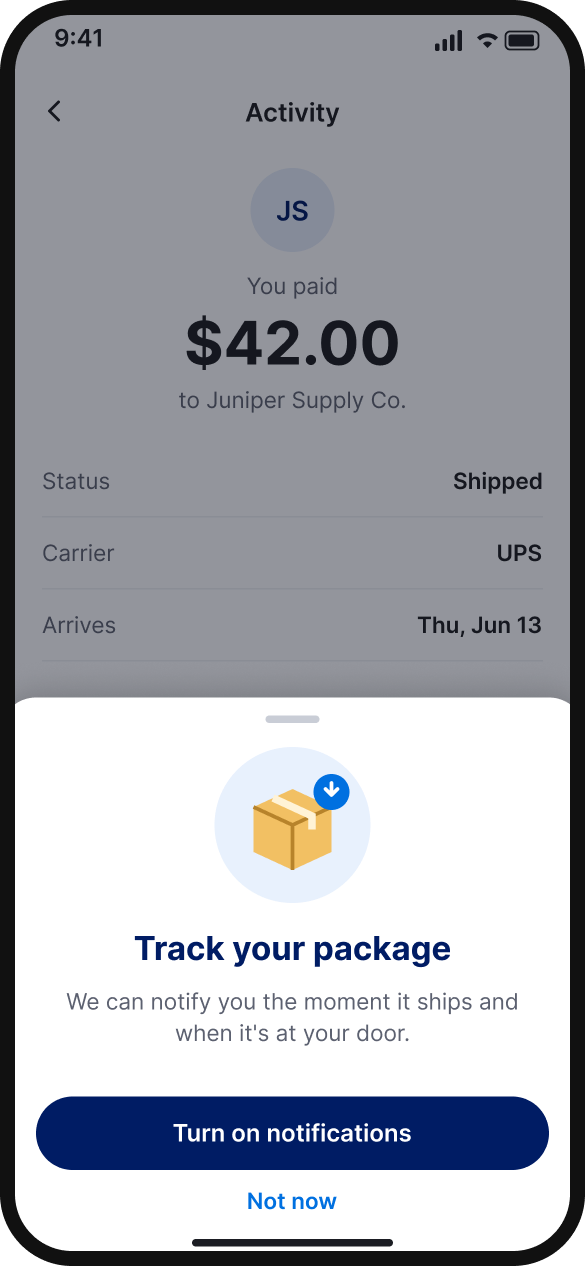
- A package the person is waiting on ships.
- Why it worked
- Everyone opening package tracking for the first time saw a soft in-app ask. iOS allows one real prompt, so we saved it for people who had already said yes. Over 80% of them then allowed it.
One ask, four moments
Package tracking shipped first. It worked well enough that other product teams added the same soft ask where it mattered to their customers: money arriving, a bill coming due, the next Pay in 4 payment.
Package tracking Shipped first
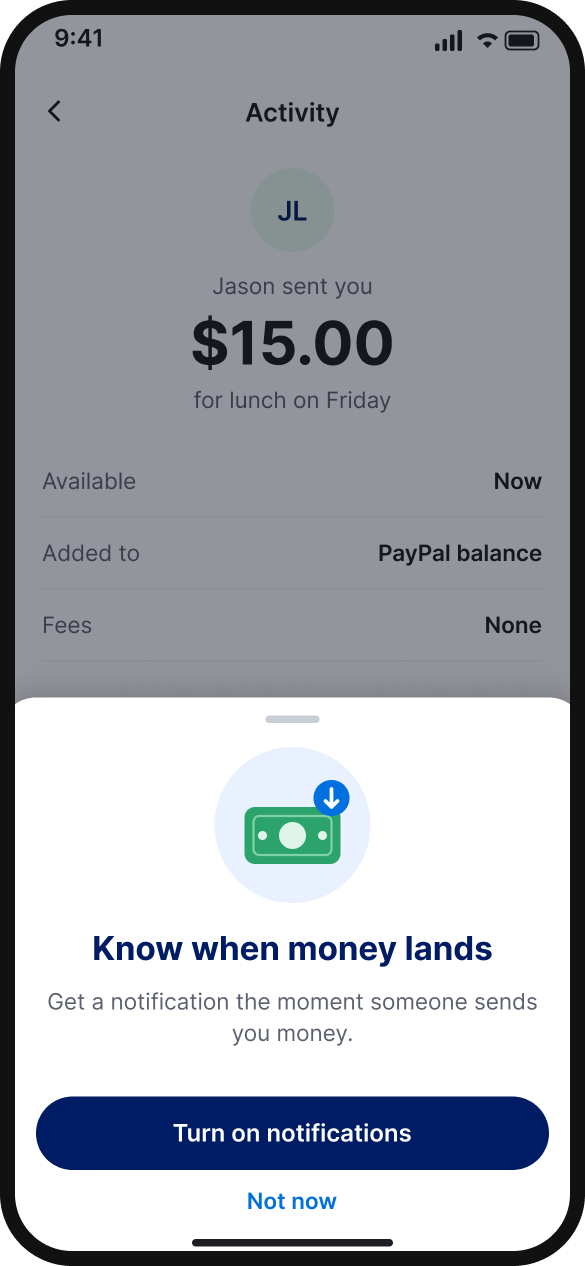
Money received
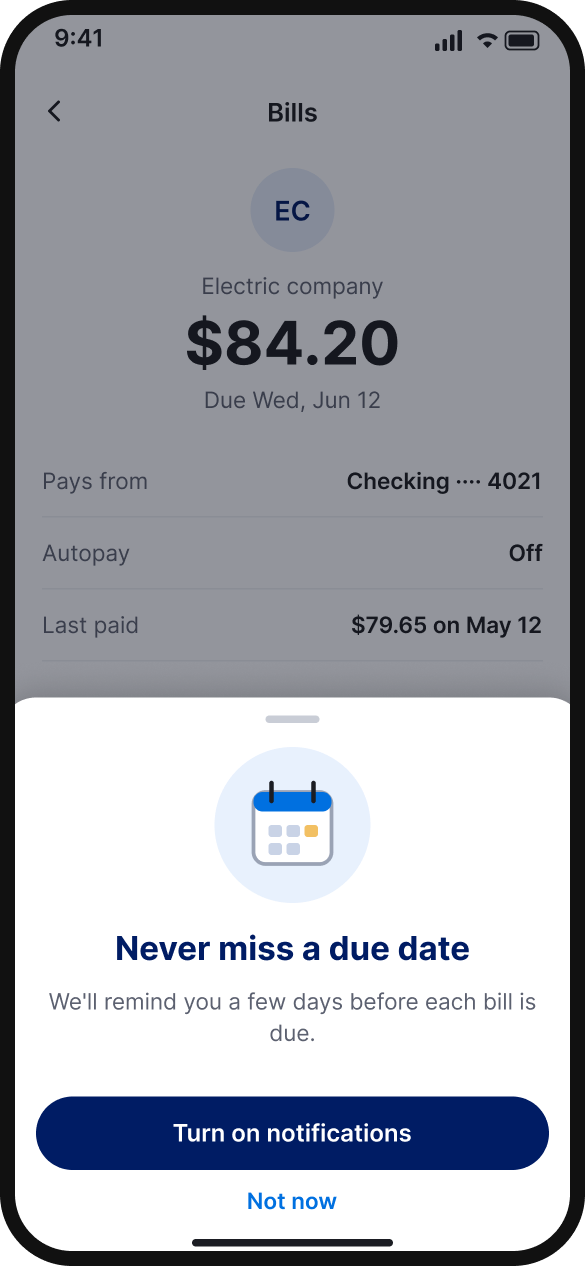
Upcoming bills
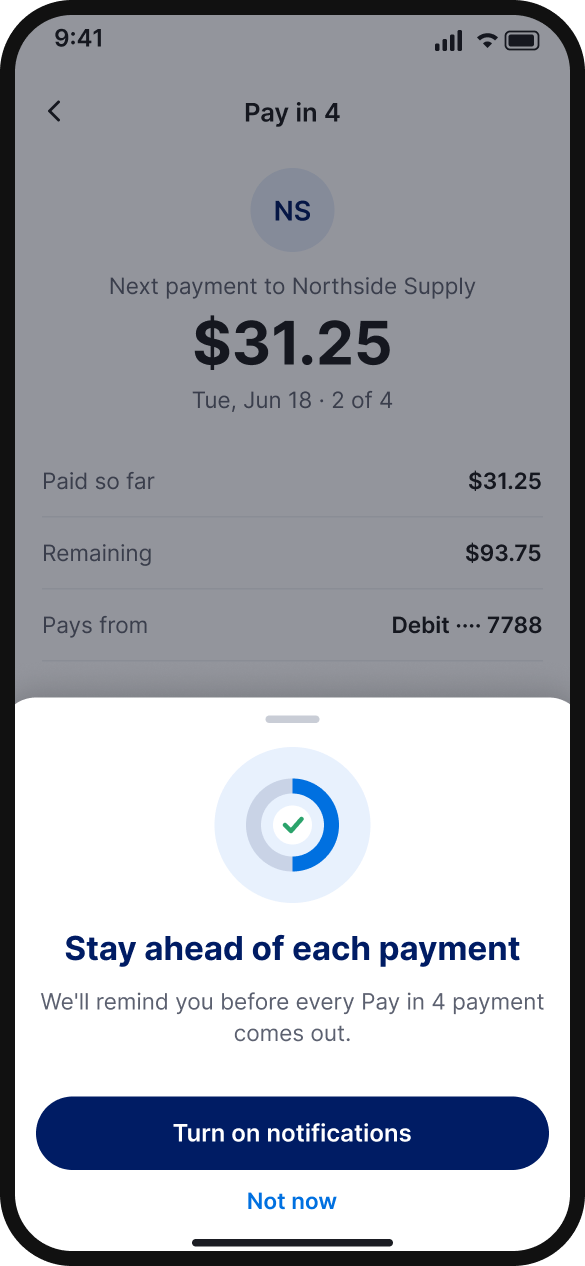
Pay in 4
The bigger bet was to ask for nothing up front. It never got a test.
At the time you couldn't open an account without adding at least one financial instrument, a bank, debit, or credit card. Customers who added a second instrument later showed higher MAU, fewer declines, and fewer negative balances. That was a correlation, since engaged people add instruments. The hypothesis was strong anyway: require no instrument up front, ask for one at first product use, and select for higher-quality accounts the way the notification move had.
The P2P team wouldn't test it. Moving the instrument step into the send-money flow could add friction at the conversion moment and cost completions. Our qualitative work and the notification result both pointed the other way. We had the evidence to make the case. What we lacked was a team willing to own the risk.
I should have called the aging signup platform itself as a business risk earlier.
Name the signup platform a product-infrastructure risk, loudly and early, in business terms. Working around it was pragmatic short-term and limiting over time. Every cycle spent designing around the monolith was a cycle not spent extending the system's reach.
Progressive reinforcement, trust-gated credit, capability-aware surfaces and the notification-proxy architecture carried into later design thinking.